Adding the CA prefix to your name will unlock infinite career options for you.
You could start a private practice, join a firm, do a partnership, and even pursue a corporate job.
Unsurprisingly, the latter is one of the most preferred options nowadays.
And If you do decide to go the corporate way, there are several job rules you can pursue, the majority of them are in the areas of Auditing, taxation, statutory, etc.
Now, the application process for these and more such job roles is dramatically different and personalized. But being a chartered accountant, there are some interview questions that you will continue to face regardless of your job domain or offer.
And so this is a quick guide to some of the most commonly asked questions to CAs in most job interviews:
Behavioural Questions
1. Tell me About yourself.
The question is usually asked when the interviewer hasn’t had the chance to scan through your resume. It’s mostly open-ended and your focus while answering it should be on highlighting the positive aspects of your professional life, such as your productive hobbies, your areas of interest, and a subtle hint at your past achievements and work experience.
A good way to make an impression is to present your own opinions on certain things about your career and why you are pursuing what you are doing right now.
The answer shouldn’t stretch more than a minute.
Here’s a sample answer.
“I come from [city] and have settled here now for my professional obligations. I pursued the CA program after my 12th which I completed from [school_name].
I did my articleship from [firm_name] where I was responsible for [work_responsibilities]. I have worked in statutory audits, internal audits, and tax audits and have covered the various aspects and operations right from Vouching to Finalization.
As a highly-driven individual, I often strive to take up opportunities that challenge me both physically and mentally.
As a result, I have also received great exposure to various clients across multiple industries.”
2. How do you think will you be able to add value to this organization?
Give examples from your previous job about your work ethic, your achievements, the clients you worked with, etc.
If you are pursuing any certifications or additional qualifications that relate to your role in the company, be sure to mention them as much as you can.
3. What are your strengths?
Always supplement the strengths you mention with real-life examples.
So for example, if you state time management as your strength, you’d follow it up with, “I tend to set personal deadlines for all my projects and I have been able to commit to ALL of them”
Some basic strengths that you could mention are:
- Team-management
- Analytical skills
- Attention to detail
- Fast-learner
- Multi-tasking (not-recommended)
- Empathetic (if you can provide a good example for it, this could be a great one)
4. What are your weaknesses?
Don’t ever try the typical approach such as, “I work too hard”, or, “I am too analytical”. This is one question that you can honestly answer albeit with some tact.
A potential answer to this can be,
“I often tend to self-criticize myself a lot. It’s something that stems from my childhood. But I am currently pursuing therapy for it and I am making a lot of progress in overcoming it”
5. What are some pros and cons of working in a team according to you?
Draw out logical pros and cons for the same but assume the stance that you can excel with or without a team.
An answer like this could work,
“Well, the obvious pros are that you get to share and amplify ideas, get feedback on your drawbacks, and get work done fast. The obvious cons are that there can arise a situation of ‘too many cooks'. Tasks are often delayed if a team is not properly organized or if team members are not answerable to each other.
In the past, I have got to work both as a team member and as an individual, and although my most productive work is when I am working alone.
Things tend to happen a lot more quickly when I am in a team.”
6. What according to you was the most difficult phase of your college life?
A very safe and bang-on answer could be,
“The most challenging phase of my college life was also one of the best ones. It was the final year because at the time I was bombarded with work and its stress. I was pursuing an articleship, I was managing my extracurricular, I had to do college project submissions, and was also preparing for my college exams.
And there was also the looming preparation for the CA finals. But that phase really activated my most productive self yet for even though there were all these challenges, I was able to traverse through them all and managed to become a stronger and more confident version of myself”
7. What prior work experience you have had?
That’s pretty much a no-brainer except for the fact that if you don’t have a lot of work experience, then it's best to mention your certifications or any other upskilling programs that you pursued.
Your priority here is to explain what you have done with the time that was supposed to be your work experience years.
If you do have work experience, try to mention all your responsibilities and achievements during your work.
8. Tell me about a difficult situation you faced in your previous company and how you solved it?
You can describe a specific situation from your articleship or internships or about a specific client.
Choose a situation that was not overly complicated and which you were able to solve rather flawlessly.
9. Where do you see yourself in 5 years?
Please for the love of god, do not say, “In your seat”. That’s an instant thumbs down.
Approach this question with a focus on skills and work domains.
Start by stating your aspirations about your career and the skills that you want to learn in the future,
If you do have managerial ambitions, then convey it to them in subtle words like,
“I see myself leading a team in the future and leading the auditing of a high-level client.”
10. List any 3 personal negative traits that you have, and what you are doing to improve them
You can afford to be honest here as long as you are not mentioning any negative traits that might directly impact your job profile.
For example,
“I don’t think I could count that many negative traits, but yes one negative trait about me that instantly comes to my mind is my inability to handle criticism from others. I often end up becoming too much upset even over slight criticism, but its something that I have been trying to cure with self-help books”
11. What are the conditions under which you do your best work? When it comes to working conditions, what do you find most challenging?
Again a straightforward answer could be,
“I do my best work in a thriving, encouraging, and positive work environment with an active competitive spirit. I can usually get along with my peers and acquaintances howsoever their behavior might be as I believe that I am excellent at dealing with people.
However, a toxic work environment where people are trying to drag each other down would be the biggest challenge for me."
12. How would you tackle such a challenge?
The follow up answer would be,
“In case I come across such a toxic work environment, my first plan of action would be to establish some serious boundaries so that other people don’t walk all over me.
Second, I would assume a formal stance while dealing in situations where people are intentionally being offensive.
My major objective would be to sustain my productivity, not let the toxicity derail my focus, and remain cordial and formal with the team to improve efficiency.
13. When comparing one company's offer to another, what factors will be important to you besides starting salary?
Being genuine yet diplomatic is the way to go here,
"The most important aspect for me will always be personal growth and a sustainable learning curve.
That being said, an equally important aspect is the work environment.
I think a company’s work culture and the opportunities it can provide to me are far greater reasons for me to choose it than the monetary compensation it can offer."
Technical Questions
14. What are the roles and responsibilities of a CA in an organization?
A CA as the official expert at accounting and auditing knowledge is responsible for key areas of financial reporting and accounts in an organization.
.jpg "roles of CA")
The chartered accountant's responsibility is to implement accounting systems and processes, prepare monthly financial reports, control the general ledger data, and ensure compliance with state revenue laws.
15. How do you calculate the total income of an assessee?
There are 5 heads of income that are generally considered while maintaining the total income of the assessee:
- Income from Salaries
- Income from House Property
- Profits from Business and Profession
- Income from Capital Gains
- Income from Other Sources
16. Is There A Criteria For Exemption From HRA?
HRA of an employee depends on the following criteria:
- Salary of the employee
- House Rent Allowance
- Rent paid by the employee
- The place where the house is taken on a rental basis.
17. Explain The Difference Between Short Term Capital Asset And Long Term Capital assets.
Short-term capital assets – Any asset owned by an individual (taxpayer) for less than 3 years since the date of transfer/ownership is referred to as a short-term capital asset. This duration should be less than 12 months in the case of shares.
Long-term capital assets – Any asset owned by an individual (taxpayer) for more than 3 years since the date of transfer to his/her name is treated as a long-term capital asset. This duration is taken as 12 months or more in the case of shares.
18. What are some allowances that are fully taxable?
Following are some compensation for employees that are completely taxable:
- Dearness Allowance
- City Compensatory Allowance
- Medical Allowance
- Lunch Allowance
- Servant Allowance
- Family Allowance
- Warder Allowance
- Overtime Allowance
- Family Allowance
19. What are The Golden Rules Of Accounting?
The golden rules of accounting help in documenting the financial transactions in ledgers. These golden rules are based on the type of account. Each transaction will have a debit and credit entry and belong to one of the following three types of accounts:
Real Account: Debit what comes in, Credit what goes out
Nominal Account: Debit all expenses and losses, credit all incomes and gains
Personal Account: Debit the giver, Credit the received
20. Explain What Is Bop in accounting?
A country's balance of payments (BoP) records all its economic transactions with the rest of the world over a given period of time, usually a year. In simple terms, it is a systematic accounting balance sheet of the country and includes both debit and credit transactions.
BoP accounting aims to determine the economy's strengths and weaknesses. You can determine the overall gains and losses from international trade by analyzing the BoP accounts of the previous year.
21. What Is The Incidence Of Tax?
The tax incidence measures how much tax is actually paid by whom. In this study, tax policies are analyzed in order to determine how price changes will affect consumers or producers, as a result of new tax policies.
- Market tax incidence refers to how taxes are distributed between buyers and sellers.
- It largely depends upon the price elasticity of demand and supply.
- In the case of elastic goods(which people purchase but are not out of necessity), the tax burden is faced by the suppliers.
- Similarly, in the case of inelastic goods(which people purchase out of necessity), the tax burden is faced by the consumers.
22. Explain what is Inflation, and how is it measured by the government bodies?
Inflation is the overall increase in prices of goods and services throughout the economy over time. It is measured by comparing the prices of goods and services currently with the past price records.
The Wholesale Price Index (WPI) and the Consumer Price Index (CPI) are used in India, to measure inflation (CPI).
- In India, the wholesale price index (WPI) is the main measure of inflation. The WPI measures the price of a representative basket of wholesale goods.
- CPI is a comprehensive measure used for the estimation of price changes in a basket of goods and services representative of consumption expenditure in an economy. The change in CPI gives a good indication of the overall inflation in the country.
23. Who is a resident or Ordinarily resident?
Residents and Ordinarily Residents are those who satisfy any one of the basic conditions and both of the following additional conditions -
Basic Conditions:
- In the relevant past year, he is in India for a period or periods amounting in all to at least 182 days.
- He is in India for 60 days or more during the relevant previous year and has also been in India for 365+ days during four previous years immediately preceding the relevant previous year.
Additional Conditions:
- He has been Resident in India for at least 2 out of 10 previous years immediately preceding the relevant previous year.
- He has been in India for 730 days or more during 7 previous years immediately preceding the relevant previous year.
24. What do you understand by Superannuation Fund? How is it taxed?
A superannuation fund is a form of employee welfare that is usually applied to very senior employees. The employee's contribution, the employer's contribution, and interest thereon are paid to the employee after the employee ceases to be an employee, and in case of death, to the employee's legal heirs.
Here’s how a superannuation fund is taxed:
- An employee’s contribution to the superannuation fund is eligible for a tax rebate under Section 80C.
- On the other hand, the employer’s contribution to the superannuation is completely exempt from taxes.
- Interest on the accumulated balance in the superannuation fund is exempt from tax.
- The amount paid to the employee in lieu of or in commutation of an annuity on his retirement on or after the specified age or on his becoming incapacitated prior to such retirement is exempt from tax.
- The amount paid by way of refund of contribution to the legal heirs on the death of the beneficiary is also exempt from tax.
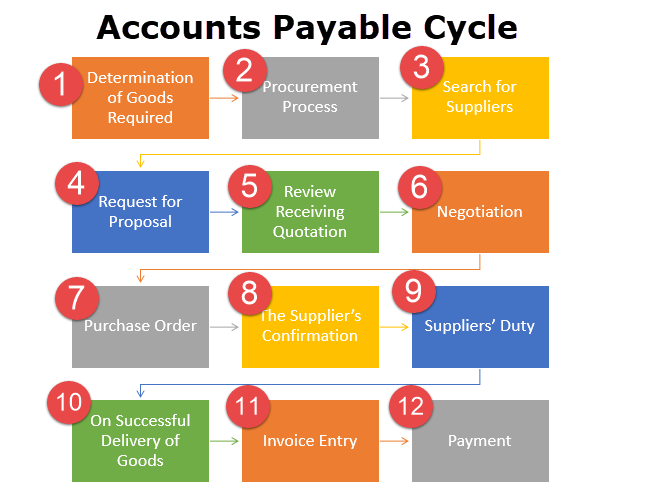
25. Explain the accounts payable cycle.
An Accounts Payable cycle also called 'Procure to Pay' or 'P2P', entails all activities related to placing orders, procuring goods for suppliers, and making final payments to suppliers.
26. What are Perpetual and Periodic Inventory systems?
Companies keep inventory on hand for production purposes or to sell on the market. It includes raw materials and finished goods. There are two types of inventory: periodic and perpetual.
The periodic inventory consists of physical counts made at various points in time, while the perpetual inventory uses point-of-sale and enterprise asset management systems to track inventory. Compared to the latter, the former is more cost-effective.
27. What are material facts in accounting?
Material facts in accounting are those facts that affect the financial statements to a great extent and thus need to be disclosed.
The material facts are the bills or other documents that form the basis of every account book. As a result, all the documents on which an accounting book is prepared are termed material facts.
28. What are accounting ethics that a CA should practice?
The conceptual framework establishes 5 principal ethics that an accounting professional should follow throughout his professional career. They are:
- Integrity.
- Objectivity.
- Professional Competence and Due Care.
- Confidentiality.
- Professional Behavior.
29. Define Assessment year and Previous Year.
Assessment year- It is a 12-month period that begins on 1st April and ends on 31st March. For example 1st April 2011 to 31st March 2012.
Previous Year- This is the year immediately preceding the assessment year. For example, income earned between 1st April 2010 and 31st March 2011 is assessed or charged to tax for A.Y. 2011-2012.
30. What are the different types of audit opinion, and when does an auditor issue each one?
Under the Standards on Auditing issued by ICAI, the auditor’s report contains either an unmodified opinion (SA 700) or one of three modified opinions (SA 705).
1. Unmodified (clean) opinion — the financial statements are prepared, in all material respects, in accordance with the applicable financial reporting framework and give a true and fair view.
2. Modified opinions depend on two questions: what caused the problem (a material misstatement, or an inability to obtain sufficient appropriate evidence), and how widespread its effects are (material but not pervasive, or material and pervasive).
| Nature of the matter | Material but not pervasive | Material and pervasive |
|---|---|---|
| Financial statements are materially misstated | Qualified opinion | Adverse opinion |
| Unable to obtain sufficient appropriate audit evidence | Qualified opinion | Disclaimer of opinion |
Examples:
- Qualified — the company has not provided for a doubtful receivable that is material but confined to one balance; or the auditor could not attend the inventory count at one branch.
- Adverse — a subsidiary has not been consolidated, affecting almost every line of the consolidated statements.
- Disclaimer — most accounting records were destroyed and could not be reconstructed, so the auditor cannot form an opinion at all.
Pervasive effects are those not confined to specific elements, or that represent a substantial proportion of the financial statements, or that relate to disclosures fundamental to users’ understanding.
A modified opinion is accompanied by a Basis for Qualified/Adverse/Disclaimer of Opinion paragraph that explains the matter and quantifies its financial effect where practicable.
Note: An Emphasis of Matter paragraph is not a modification. Interviewers often check whether you understand this distinction.
31. What is the difference between Key Audit Matters, an Emphasis of Matter paragraph and an Other Matter paragraph in an auditor’s report?
All three are communications in the auditor’s report that do not modify the opinion, but they serve different purposes.
Key Audit Matters (SA 701)
- Matters that, in the auditor’s professional judgement, were of most significance in the audit of the current period, selected from matters communicated to those charged with governance.
- Typically areas of higher assessed risk, significant judgements such as impairment of goodwill, revenue recognition for complex contracts, or significant events during the year.
- Required for audits of listed entities, and when the auditor otherwise decides or is required to communicate them.
- Each KAM describes why the matter was significant and how it was addressed in the audit.
Emphasis of Matter paragraph (SA 706)
- Draws users’ attention to a matter that is appropriately presented or disclosed in the financial statements and is fundamental to their understanding.
- Examples: uncertainty relating to the outcome of major litigation, a major catastrophe affecting the entity, or early application of a new accounting standard with a pervasive effect.
- The auditor must have obtained sufficient appropriate evidence that the matter is not materially misstated.
Other Matter paragraph (SA 706)
- Refers to a matter not presented or disclosed in the financial statements that is relevant to users’ understanding of the audit, the auditor’s responsibilities or the report.
- Examples: the prior year was audited by another auditor, or reliance on another auditor for certain branches or subsidiaries.
Key interplay: a matter that is a KAM should be reported as a KAM, not as an Emphasis of Matter. A material uncertainty related to going concern is reported in a separate section under SA 570, not as a KAM or Emphasis of Matter.
Note: Remember the one-line summary: KAM explains the audit, Emphasis of Matter highlights a disclosure, Other Matter adds context outside the financial statements.
32. Explain the audit risk model and the relationship between inherent risk, control risk and detection risk.
Audit risk is the risk that the auditor expresses an inappropriate opinion when the financial statements are materially misstated. The auditor aims to reduce it to an acceptably low level.
Audit risk = Inherent risk x Control risk x Detection risk
Components:
- Inherent risk — the susceptibility of an assertion to material misstatement before considering controls. It is higher for complex estimates (fair values, provisions), non-routine transactions, cash, and items prone to fraud.
- Control risk — the risk that the entity’s internal controls will not prevent, or detect and correct, a misstatement on time.
- Detection risk — the risk that the auditor’s own procedures will not detect a misstatement that exists.
Inherent risk and control risk together form the risk of material misstatement, assessed under SA 315. These are the entity’s risks; the auditor can assess them but cannot change them.
The inverse relationship: detection risk is the only component the auditor controls, through the nature, timing and extent of substantive procedures (SA 330). The higher the assessed risk of material misstatement, the lower the acceptable detection risk.
| Risk of material misstatement | Acceptable detection risk | Audit response |
|---|---|---|
| High | Low | More persuasive evidence, larger samples, tests closer to year end, experienced staff |
| Low | High | Fewer tests, more reliance on controls and analytical procedures, interim testing |
Example: revenue in a company with aggressive sales targets has high inherent risk. If its controls are also weak, the auditor must lower detection risk by performing extensive cut-off testing, confirmations and detailed vouching.
Note: Even when risk is assessed as low, SA 330 requires some substantive procedures for every material class of transactions, account balance and disclosure.
33. What is the difference between tests of controls and substantive procedures in an audit?
Both are responses to assessed risks under SA 330, but they answer different questions.
Tests of controls check whether the entity’s internal controls operated effectively throughout the period. They are performed when the auditor plans to rely on controls to reduce substantive testing, or when substantive procedures alone cannot give sufficient evidence (for example, in highly automated systems).
- Inspecting a sample of purchase orders for evidence of approval by an authorised person.
- Reperforming a bank reconciliation to check that the review was genuine.
- Observing the physical inventory count process.
- Testing IT general controls such as user access and change management.
Substantive procedures are designed to detect material misstatements at the assertion level. They are of two types:
- Tests of details — vouching, confirmations, physical verification, recalculation, cut-off testing. Example: vouching a sample of sales to invoices, dispatch documents and customer receipts.
- Substantive analytical procedures — developing an expectation and comparing it with recorded amounts. Example: expected interest cost equals average borrowings multiplied by the average interest rate.
| Basis | Tests of controls | Substantive procedures |
|---|---|---|
| Objective | Operating effectiveness of controls | Detect material misstatement |
| Focus | How a transaction was processed | Whether the amount is right |
| When mandatory | Only when relying on controls or when substantive tests alone are insufficient | Always, for each material class, balance and disclosure |
| Result of failure | Increase substantive testing | Propose adjustment or modify opinion |
Most audits use a combined approach: controls testing for high-volume routine transactions and substantive testing for balances and judgemental areas.
Note: A control deviation is not a misstatement. A missing approval signals a weak control, while a wrong amount is a misstatement — interviewers like to test this difference.
34. What is the difference between vouching and verification, and how would you verify inventory and fixed assets?
Vouching means examining documentary evidence to check that recorded transactions are genuine, properly authorised, correctly recorded and relate to the entity’s business. It concerns transactions during the year. For example, a purchase entry is vouched to the purchase order, goods receipt note, supplier invoice and payment record.
Verification means confirming the existence, ownership (rights), valuation and presentation of assets and liabilities at the balance sheet date. It concerns balances.
| Basis | Vouching | Verification |
|---|---|---|
| Subject | Transactions | Assets and liabilities |
| Timing | Throughout the year | Mainly at the balance sheet date |
| Key assertions | Occurrence, accuracy, authorisation | Existence, rights, valuation, completeness |
| Evidence | Invoices, vouchers, contracts | Physical inspection, title documents, confirmations, valuation reports |
Verifying inventory (SA 501):
- Attend the physical count, observe management’s procedures and perform test counts in both directions — from records to the floor and from the floor to records.
- Check cut-off using the last goods received and dispatched documents before the count.
- Identify damaged, obsolete or slow-moving items and test valuation at the lower of cost and net realisable value.
- Confirm stock held by third parties, and exclude goods held on behalf of others.
Verifying fixed assets:
- Physically inspect a sample of assets from the fixed asset register, and trace a sample from the floor to the register.
- Examine title deeds, registration certificates and lease agreements for ownership.
- Check additions against invoices and capitalisation policy, and disposals against sale documents.
- Recompute depreciation and review impairment indicators.
- Check reporting requirements under CARO on physical verification and title deeds of immovable property.
Note: The direction of testing matters: from records to documents tests occurrence, while from documents to records tests completeness.
35. What are external confirmations under SA 505, and how do positive and negative confirmation requests differ?
An external confirmation is audit evidence obtained as a direct written response to the auditor from a third party. Because it comes from an independent source outside the entity, it is generally more reliable than internal evidence. SA 505 sets out how auditors should use it.
Common uses: bank balances and borrowings, trade receivables and payables, loans, inventory held by third parties, investments held by custodians, and legal matters confirmed by lawyers.
Types of confirmation request:
- Positive confirmation — the confirming party must reply in every case, either agreeing with the stated information or providing the correct figure. A “blank” variant asks the party to fill in the balance, which gives stronger evidence but may reduce response rates.
- Negative confirmation — the party replies only if it disagrees with the information. It gives less persuasive evidence and may be used as the sole substantive procedure only when all of these apply: the risk of material misstatement is low, the population consists of a large number of small, homogeneous balances, a very low exception rate is expected, and there is no reason to believe recipients will ignore the request.
Controlling the process:
- The auditor selects the items, prepares and sends the requests, and receives replies directly — not through the client.
- Addresses and contact details are verified independently.
- Electronic confirmations must be assessed for reliability.
When things go wrong:
- Management refuses to let the auditor send a request — the auditor asks for the reasons, evaluates their validity and the implications for fraud risk, and performs alternative procedures. If these are not possible, it may affect the opinion.
- Non-response — perform alternative procedures such as checking subsequent cash receipts, shipping documents and invoices for receivables.
- Exceptions — investigate each difference to see whether it is a timing difference or a misstatement.
Note: Mention that many firms now use digital confirmation platforms, which improve speed and reduce the risk of intercepted or fabricated responses.
36. How would you audit revenue, and what cut-off procedures would you perform around the year end?
Revenue is usually the most important line in the statement of profit and loss and a common area for misstatement. SA 240 requires the auditor to presume a risk of fraud in revenue recognition unless that presumption is rebutted with reasons.
1. Understand the business and policy
- Identify revenue streams and contract terms — sale of goods, services, subscriptions, export sales.
- Check that the accounting policy follows Ind AS 115 (or AS 9 for non-Ind AS entities), including timing of transfer of control and treatment of discounts and returns.
2. Evaluate and test controls over the order-to-cash cycle — order approval, credit limits, dispatch, invoicing and price master changes.
3. Substantive analytical procedures
- Compare month-wise revenue, gross margin and product mix with the prior year and budget.
- Reconcile revenue as per books with GST returns (GSTR-1 and GSTR-3B) and investigate differences.
4. Tests of details
- Vouch a sample of sales entries to customer orders, invoices, e-way bills or delivery proofs, and subsequent receipts.
- Trace a sample of dispatch documents to sales entries to test completeness.
- Confirm receivable balances with major customers.
- Review large credit notes issued after year end, which may indicate that earlier sales were not genuine.
5. Cut-off testing
- Select dispatches and invoices from the last few days before and the first few days after the year end.
- Check that each is recorded in the correct period, based on when control transferred to the customer.
- Look out for goods billed but not shipped (bill-and-hold), and goods shipped just before year end and returned shortly after.
6. Journal entry testing — review manual entries to revenue, especially those posted at year end, by senior staff or outside normal hours.
Note: Relate your answer to a real engagement from your articleship, such as the sample size you used or an actual cut-off error you found.
37. What are the indicators of a going concern problem, and how does an auditor respond under SA 570?
The going concern basis assumes that an entity will continue in operation for the foreseeable future. Under SA 570, the auditor must obtain sufficient appropriate evidence about whether management’s use of this basis is appropriate and whether a material uncertainty exists.
Indicators that may cast doubt:
- Financial — net liability or net current liability position; fixed-term borrowings nearing maturity without realistic prospects of renewal; negative operating cash flows; substantial operating losses; default on loan repayments or classification as an NPA; inability to pay creditors on time; arrears or discontinuance of dividends.
- Operating — loss of key management, a major market, key customer, licence or principal supplier; labour difficulties; shortages of important supplies.
- Other — non-compliance with capital or statutory requirements; pending legal or regulatory proceedings that could result in claims the entity cannot meet; changes in law or government policy; initiation of insolvency proceedings.
Auditor’s response:
- Evaluate management’s assessment, which should cover at least twelve months from the date of the financial statements.
- Review management’s plans — refinancing, sale of assets, cost reductions, promoter support — and assess whether they are feasible.
- Examine cash flow forecasts, subsequent events, loan agreements, board minutes and correspondence with lenders.
- Obtain written representations from management about their plans.
Reporting outcomes:
| Conclusion | Effect on the report |
|---|---|
| Basis appropriate, no material uncertainty | Unmodified opinion |
| Basis appropriate, material uncertainty adequately disclosed | Unmodified opinion with a separate section “Material Uncertainty Related to Going Concern” |
| Material uncertainty not adequately disclosed | Qualified or adverse opinion |
| Going concern basis inappropriate | Adverse opinion |
Note: CARO also requires the auditor to report whether any material uncertainty exists on the company’s ability to meet liabilities falling due within one year, based on ageing and financial ratios.
38. What is the auditor’s reporting responsibility on internal financial controls under Section 143(3)(i) of the Companies Act 2013?
Section 143(3)(i) of the Companies Act, 2013 requires the statutory auditor to state in the audit report whether the company has adequate internal financial controls with reference to financial statements in place, and whether those controls were operating effectively.
Scope: The auditor’s reporting covers internal financial controls over financial reporting (ICFR) — controls that give reasonable assurance about the reliability of financial reporting. It does not extend to every operational control. ICAI’s Guidance Note on Audit of Internal Financial Controls over Financial Reporting explains how to perform this audit alongside the financial statement audit.
Applicability and exemptions: The requirement applies broadly, but notifications have exempted one person companies, small companies, and private companies whose turnover and borrowings are below prescribed limits. Check the current exemption notification before concluding on any specific company.
Responsibilities:
- Board and management — design, implement and maintain adequate internal financial controls. Section 134(5)(e) requires directors of listed companies to confirm in the Directors’ Responsibility Statement that such controls are adequate and operating effectively.
- Auditor — obtain reasonable assurance about the adequacy and operating effectiveness of those controls and express an opinion in a separate annexure to the audit report.
How the audit is performed:
- Understand the entity’s control framework, often based on COSO or an internal risk and control matrix.
- Identify significant accounts and relevant assertions.
- Test entity-level controls, process-level controls and IT general controls through walkthroughs and tests of operating effectiveness.
- Evaluate identified deficiencies — deficiency, significant deficiency or material weakness.
Reporting: If one or more material weaknesses exist, the auditor issues a modified opinion on internal financial controls. The opinion on the financial statements may still be unmodified if substantive work shows no material misstatement.
Note: Interviewers often ask whether an IFC qualification automatically qualifies the financial statements opinion. The answer is no — the two opinions are separate.
39. What is a tax audit under the Income Tax Act, who needs one, and what do Forms 3CA, 3CB and 3CD cover?
A tax audit is an audit of a taxpayer’s books of account by a practising chartered accountant, required by Section 44AB of the Income-tax Act, 1961. Its purpose is to verify that books are properly maintained and to report specified particulars that help the tax department assess the correct income.
Who needs a tax audit:
- A person carrying on business whose total sales, turnover or gross receipts exceed the prescribed limit. A higher limit applies where cash receipts and cash payments are each within 5% of the total.
- A person carrying on a profession whose gross receipts exceed the prescribed limit.
- A person who declares profits lower than the presumptive rate under the presumptive taxation provisions and whose income exceeds the basic exemption limit, in the cases specified.
Limits are revised by Finance Acts, so always quote the figure applicable for the relevant year.
Forms:
| Form | Used when |
|---|---|
| Form 3CA | The taxpayer’s accounts are already required to be audited under another law, such as a company under the Companies Act |
| Form 3CB | The taxpayer is not required to get accounts audited under any other law, such as a proprietor or partnership firm |
| Form 3CD | The statement of particulars attached to either audit report |
Key items reported in Form 3CD:
- Method of accounting and valuation of closing stock, and any change in them.
- Depreciation allowable under tax law, block by block.
- Amounts inadmissible — for example, payments without TDS, disallowances under Section 43B, and cash payments above prescribed limits.
- Loans and deposits taken or repaid in cash in breach of the relevant provisions.
- Details of TDS and TCS compliance, key ratios, and quantitative details of goods traded or manufactured.
The report must be filed electronically by the specified date, and failure attracts a penalty linked to turnover, subject to a cap.
Note: The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026 and renumbers these provisions and forms, but the concept of a tax audit continues. Clarify which law applies to the year you are discussing.
40. Which expenses are allowed only on actual payment under Section 43B of the Income Tax Act?
Section 43B of the Income-tax Act, 1961 overrides the mercantile (accrual) system for certain expenses. Even if a business records them on an accrual basis, they are deductible only in the year they are actually paid. The purpose is to stop taxpayers claiming deductions for liabilities, especially statutory dues, that they do not pay.
Expenses covered:
- Taxes, duties, cess and fees payable under any law (for example, property tax, customs duty, and GST where it is charged to profit and loss).
- Employer’s contribution to provident fund, superannuation fund, gratuity fund or any other employee welfare fund.
- Bonus or commission payable to employees.
- Interest on loans or borrowings from public financial institutions, state financial corporations, scheduled banks, co-operative banks and certain NBFCs.
- Leave encashment payable to employees.
- Payments to Indian Railways for the use of railway assets.
- Amounts payable to micro and small enterprises beyond the time limit specified in Section 15 of the MSMED Act, 2006.
Relief for payment before filing the return: If the amount is paid on or before the due date for filing the income tax return for that year, the deduction is allowed in the year the liability was incurred. Otherwise, it is allowed in the year of actual payment.
Important exception: the relief for payment before the return due date does not apply to dues payable to micro and small enterprises. If such a supplier is not paid within the MSMED Act time limit (15 days without an agreement, up to 45 days with a written agreement), the expense is allowed only in the year it is actually paid.
Related point: the employee’s share of PF and ESI deducted from salary is treated as the employer’s income and is deductible only if deposited by the due date under the relevant welfare law, not the return filing date.
Note: These disallowances are reported in Form 3CD during a tax audit, so be ready to explain how you would verify payment dates with challans and bank statements.
41. Explain the presumptive taxation schemes for small businesses and professionals under Sections 44AD, 44ADA and 44AE.
Presumptive taxation lets small taxpayers declare income at a fixed percentage of turnover or a fixed amount, instead of maintaining detailed books and getting them audited. It reduces compliance cost for both taxpayers and the tax department. The main schemes under the Income-tax Act, 1961 are:
| Section | Who can opt | Deemed income |
|---|---|---|
| 44AD | Resident individuals, HUFs and partnership firms (not LLPs) carrying on an eligible business, with turnover within the prescribed limit | 8% of turnover, or 6% of turnover received through banking or digital channels |
| 44ADA | Resident individuals and partnership firms (not LLPs) in specified professions such as legal, medical, engineering, architecture, accountancy and technical consultancy, with gross receipts within the prescribed limit | 50% of gross receipts |
| 44AE | Taxpayers owning not more than ten goods carriages at any time during the year | A fixed amount per vehicle for each month or part of a month it is owned (for heavy goods vehicles, based on gross vehicle weight) |
Key features:
- The taxpayer can declare a higher income than the presumptive figure.
- All deductions under Sections 30 to 38 are deemed to have been allowed, so no separate expense claims are made.
- No need to maintain books under Section 44AA or get a tax audit, in most cases.
- Advance tax can be paid in a single instalment by 15 March.
- Turnover limits are higher where cash receipts are within 5% of total receipts. These limits are revised by Finance Acts, so quote the figure for the relevant year.
Restriction under 44AD: if a taxpayer opts for the scheme and then declares lower profits in any of the next five years, it cannot opt back in for the following five years. It must also maintain books and get a tax audit if its income exceeds the basic exemption limit.
Excluded: commission and brokerage businesses, agency businesses, and companies are not eligible for 44AD.
Note: The Income-tax Act, 2025 continues presumptive taxation with renumbered sections from 1 April 2026. Mention this if the interviewer asks about the current law.
42. What are the rules for set-off and carry forward of losses under the Income Tax Act?
Set-off means adjusting a loss against income of the same year; carry forward means taking an unadjusted loss to future years. The Income-tax Act, 1961 applies this in a fixed order.
Step 1 — Intra-head set-off (Section 70): a loss from one source is set off against income from another source under the same head. Exceptions:
- Speculation business loss can be set off only against speculation income.
- Long-term capital loss can be set off only against long-term capital gains; short-term capital loss can be set off against both short-term and long-term gains.
- Loss from owning and maintaining race horses can be set off only against income from that activity.
- No loss can be set off against winnings from lotteries, crossword puzzles or similar income.
Step 2 — Inter-head set-off (Section 71): remaining losses can be set off against income under other heads, with these limits:
- Business loss cannot be set off against salary income.
- Capital loss cannot be set off against any other head.
- Loss under “Income from House Property” can be set off against other heads only up to ₹2 lakh in a year; this is not available under the new tax regime.
Step 3 — Carry forward:
| Loss | Carry forward period | Set off against |
|---|---|---|
| House property | 8 assessment years | House property income only |
| Business (non-speculative) | 8 assessment years | Business income |
| Speculation business | 4 assessment years | Speculation income only |
| Capital losses | 8 assessment years | Capital gains (LTCL only against LTCG) |
| Unabsorbed depreciation | No time limit | Any income except salary and casual winnings |
Conditions: business, speculation and capital losses can be carried forward only if the return of loss is filed by the due date. For closely held companies, a change in shareholding beyond 49% can prevent carry forward of business losses.
Note: The Income-tax Act, 2025 carries forward these principles from 1 April 2026 using “tax year” instead of assessment year. State which Act you are applying.
43. When is IGST charged instead of CGST and SGST, and how is the place of supply determined under GST?
GST is a destination-based tax. Whether a supply attracts CGST plus SGST/UTGST or IGST depends on comparing the location of the supplier with the place of supply.
- Intra-state supply — supplier and place of supply in the same state or union territory: CGST plus SGST (or UTGST).
- Inter-state supply — supplier and place of supply in different states: IGST.
- Always treated as inter-state — imports into India, exports, and supplies to or by a Special Economic Zone developer or unit.
Place of supply of goods (Section 10 of the IGST Act):
- Where goods move: the location where movement ends for delivery to the recipient.
- Bill-to-ship-to: where goods are delivered to a third person on the instructions of a buyer, the place of supply is the buyer’s principal place of business.
- Where goods do not move: the location of the goods at the time of delivery.
- Goods assembled or installed at site: the place of installation.
Place of supply of services (Section 12, both parties in India):
- General rule — to a registered person: the recipient’s location; to an unregistered person: the recipient’s address on record, or otherwise the supplier’s location.
- Specific rules — services related to immovable property (such as construction or hotel stays): where the property is located; restaurant and personal services: where performed; admission to events: where the event is held; passenger transport for an unregistered recipient: where the passenger embarks.
Example: a Delhi-based supplier sells goods to a Delhi buyer, with instructions to deliver to the buyer’s customer in Punjab. Under bill-to-ship-to, the place of supply is Delhi (the buyer’s location), so CGST and SGST apply on the first leg.
Wrong tax head paid: if IGST was paid where CGST and SGST were due, or vice versa, the correct tax must be paid and a refund of the wrongly paid tax claimed. No interest is payable on the correct tax.
Note: Place of supply errors are among the most common GST issues, because credit taken by the recipient depends on the supplier charging the right tax head.
44. What is the difference between a composite supply and a mixed supply under GST, and how is each taxed?
When two or more goods or services are supplied together for a single price, GST law uses two concepts to decide the applicable rate.
Composite supply (Section 2(30) of the CGST Act)
- Two or more taxable supplies that are naturally bundled and supplied together in the ordinary course of business.
- One of them is the principal supply — the predominant element; the others are ancillary.
- Taxed at the rate applicable to the principal supply (Section 8(a)).
- Examples: goods sold with packing, transport and insurance, where goods are the principal supply; a works contract, which the law treats as a supply of services.
Mixed supply (Section 2(74))
- Two or more individual supplies made together for a single price, where the items are not naturally bundled and could be sold separately.
- Taxed at the rate of the item attracting the highest rate of tax (Section 8(b)).
- Example: a festive gift hamper containing sweets, chocolates, dry fruits and aerated drinks sold for one price.
| Basis | Composite supply | Mixed supply |
|---|---|---|
| Nature | Naturally bundled | Not naturally bundled |
| Principal supply | Exists | No principal supply |
| Rate | Rate of the principal supply | Highest rate among the items |
| Priced separately | Would normally not be | Could be, but sold for a single price |
Tests for “naturally bundled”: whether customers normally expect the items together, whether they are usually advertised as a package, whether they are sold separately in the market, and whether one item is only a means to better enjoy the main item.
If items are sold at separate prices on the same invoice, neither concept applies — each item is taxed at its own rate.
Note: Classification disputes often reach advance ruling authorities, so the decision should be documented with facts about the industry practice.
45. What are the main GST returns a business files, and which reconciliations should be done before filing them?
A regular GST taxpayer files a set of periodic and annual returns, and the data in them must agree with the books of account.
Main returns and statements:
- GSTR-1 — details of outward supplies (invoices, credit and debit notes, exports). Filed monthly, or quarterly by eligible small taxpayers under the QRMP scheme.
- GSTR-3B — summary return declaring outward supplies, input tax credit claimed and net tax paid. Filed monthly or quarterly.
- GSTR-2B — an auto-drafted, static statement of input tax credit available, generated from suppliers’ GSTR-1. It is not filed but is the basis for claiming ITC.
- GSTR-9 — annual return summarising the year.
- GSTR-9C — reconciliation statement between audited financial statements and GSTR-9, self-certified, for taxpayers above the prescribed turnover.
- Others: CMP-08 and GSTR-4 for composition taxpayers, GSTR-7 for tax deductors, GSTR-8 for e-commerce operators collecting TCS.
Key reconciliations before filing:
- Sales register vs GSTR-1 vs GSTR-3B — every invoice, credit note and debit note should appear in both returns, with the same tax values.
- E-invoices and e-way bills vs GSTR-1 — for taxpayers covered by e-invoicing, IRN data auto-populates GSTR-1 and should match books.
- Purchase register vs GSTR-2B — ITC should be claimed only for invoices reflected in GSTR-2B; follow up with suppliers for missing invoices.
- ITC claimed vs eligibility — reverse blocked credits, credits on exempt supplies, and credits for suppliers unpaid beyond 180 days.
- Reverse charge liability — confirm it has been identified from expense ledgers and paid in cash.
- Books vs GST ledgers — balances in the electronic cash, credit and liability ledgers on the portal should match the GST ledgers in the books.
Annual reconciliation: total turnover in the audited financial statements is reconciled with turnover reported in GST returns, explaining items such as unbilled revenue, advances and non-GST income.
Note: Return formats and filing features change frequently, so mention that you track GSTN advisories and CBIC notifications as part of your routine.
46. Which companies must spend on Corporate Social Responsibility under Section 135 of the Companies Act 2013, and how is unspent CSR money treated?
Section 135 of the Companies Act, 2013 made India one of the first countries to mandate CSR spending.
Applicability: a company must comply if, in the immediately preceding financial year, it had any of the following:
- Net worth of ₹500 crore or more; or
- Turnover of ₹1,000 crore or more; or
- Net profit of ₹5 crore or more.
Obligation:
- Spend at least 2% of average net profits of the three immediately preceding financial years (computed under Section 198), on activities listed in Schedule VII — such as education, health care, rural development, environmental sustainability and contributions to specified funds.
- Constitute a CSR Committee of the board. It is not required where the CSR obligation does not exceed ₹50 lakh; the board then performs its functions.
- Approve a CSR policy and disclose the CSR activities in the board’s report.
- Activities for employees only, activities outside India (with limited exceptions) and contributions to political parties do not count as CSR.
Treatment of unspent amounts:
| Situation | Required action |
|---|---|
| Unspent amount relates to an ongoing project | Transfer to a special Unspent CSR Account within 30 days of the end of the financial year; spend within the next three financial years, after which any balance goes to a Schedule VII fund |
| Unspent amount not related to an ongoing project | Transfer to a fund specified in Schedule VII within six months of the end of the financial year |
| Excess spent over the obligation | May be set off against the requirement of the next three financial years, subject to conditions |
Non-compliance attracts monetary penalties on the company and officers in default.
Accounting and tax: CSR spending is charged to the statement of profit and loss as an expense. It is not deductible as a business expense under the Income Tax Act, although some contributions may qualify for separate deductions.
Note: Auditors report on unspent CSR amounts under CARO, so this topic comes up in statutory audit interviews as well.
48. Out of which profits can a company declare dividend under Section 123 of the Companies Act 2013, and what conditions apply?
Section 123 of the Companies Act, 2013, together with the Companies (Declaration and Payment of Dividend) Rules, 2014, sets out when and how a company may pay dividend.
Sources of dividend:
- Profits of the current financial year, after providing for depreciation in accordance with Schedule II;
- Undistributed profits of previous financial years, after providing for depreciation; or
- Both; or money provided by the Central or a State Government under a guarantee.
Key conditions:
- Before declaring dividend out of current year profits, any carried-forward losses and unprovided depreciation of previous years must be set off against those profits.
- Unrealised gains, notional gains, revaluation of assets and changes in carrying amounts from fair value measurement are excluded when computing profits available for dividend.
- Transfer of profits to reserves before declaring dividend is at the company’s discretion.
- Dividend can be paid only out of free reserves, not from the securities premium or capital reserves.
Dividend out of accumulated profits in a year of inadequate profits — the Rules restrict it, for example:
- The rate should not exceed the average rate of the three preceding years (unless no dividend was paid in those years).
- The amount drawn should not exceed one-tenth of paid-up capital plus free reserves.
- Current year losses must be set off first.
Interim dividend: the board may declare it during the year out of surplus in the profit and loss account or current year profits. If the company has incurred a loss up to the quarter before declaration, the rate cannot exceed the average of the three preceding years.
Payment timelines:
- Deposit the dividend in a separate bank account within five days of declaration.
- Pay shareholders within 30 days of declaration (Section 127).
- Unpaid amounts are moved to an Unpaid Dividend Account and, after seven years, to the Investor Education and Protection Fund.
Note: Dividend is now taxable in the hands of shareholders, and the company deducts TDS where required — mention this if the interviewer links company law to tax.
49. Which companies must follow Ind AS, and what are the key differences between Ind AS and the earlier Indian Accounting Standards?
Ind AS are converged with IFRS and notified under the Companies (Indian Accounting Standards) Rules, 2015. Other companies continue to follow Accounting Standards (AS) under the Companies (Accounting Standards) Rules.
Applicability roadmap for companies:
- Phase I (from financial year 2016-17): companies, listed or unlisted, with net worth of ₹500 crore or more, and their holding, subsidiary, joint venture and associate companies.
- Phase II (from 2017-18): all listed companies and companies in the process of listing (other than those on SME exchanges), unlisted companies with net worth of ₹250 crore or more, and their group companies.
- Voluntary adoption is allowed, but once a company moves to Ind AS it cannot go back.
- Banks, insurance companies and NBFCs follow separate roadmaps set by their regulators.
Key differences:
| Area | Ind AS | Earlier AS |
|---|---|---|
| Measurement | Wider use of fair value (Ind AS 113, 109) | Mostly historical cost |
| Revenue | Five-step model under Ind AS 115 | Risks and rewards under AS 9 |
| Leases (lessee) | Right-of-use asset and lease liability under Ind AS 116 | Operating leases kept off balance sheet under AS 19 |
| Receivables | Expected credit loss model | Incurred loss based provisioning |
| Business combinations | Acquisition method at fair value; goodwill tested for impairment, not amortised | Amalgamation accounting under AS 14; goodwill often amortised |
| Other comprehensive income | Required statement of OCI | No OCI concept |
| Prior period errors | Retrospective restatement | Shown in the current year’s profit and loss |
| Extraordinary items | Prohibited | Permitted under AS 5 |
Carve-outs: Ind AS differs from IFRS in a few areas to suit Indian conditions — for example, certain options on classification of loans and on bargain purchase gains.
Note: Ind AS applicability is tested on net worth, so remember that the thresholds apply at the standalone level and pull in group companies once triggered.
50. How do NPV and IRR differ as capital budgeting tools, and which should you prefer when they give conflicting results?
Net Present Value (NPV) is the present value of expected cash inflows minus the present value of cash outflows, discounted at the company’s cost of capital. A project with positive NPV adds value and should be accepted.
Internal Rate of Return (IRR) is the discount rate at which NPV equals zero. A project is accepted if its IRR exceeds the cost of capital.
For a single, independent project with conventional cash flows (one outflow followed by inflows), both methods give the same accept or reject decision. Conflicts arise when ranking mutually exclusive projects.
Why conflicts arise:
- Scale — a small project may have a high IRR but a small NPV, while a large project has a lower IRR but a much bigger NPV.
- Timing — projects with early cash inflows tend to have higher IRRs.
- Unequal lives — projects of different durations are not directly comparable.
- Reinvestment assumption — NPV assumes cash flows are reinvested at the cost of capital, which is realistic; IRR assumes reinvestment at the IRR itself, which may be unrealistically high.
- Non-conventional cash flows — if cash flows change sign more than once, a project can have multiple IRRs or none.
Example (cost of capital 12%):
| Project | Investment | IRR | NPV |
|---|---|---|---|
| A | ₹10 lakh | 25% | ₹3 lakh |
| B | ₹50 lakh | 18% | ₹8 lakh |
IRR ranks A higher, but NPV ranks B higher. If the projects are mutually exclusive and capital is available, choose B, because it adds ₹8 lakh to shareholder wealth compared with ₹3 lakh.
Conclusion: NPV is generally preferred because it measures the absolute increase in value and uses a realistic reinvestment rate. IRR remains popular because it is expressed as a percentage and is easy to communicate.
Note: Mention Modified IRR, which fixes the reinvestment problem, and the Profitability Index, which is useful when capital is rationed.


 Log in with Google
 Log in with LinkedIn